

Product evolution with Deedster
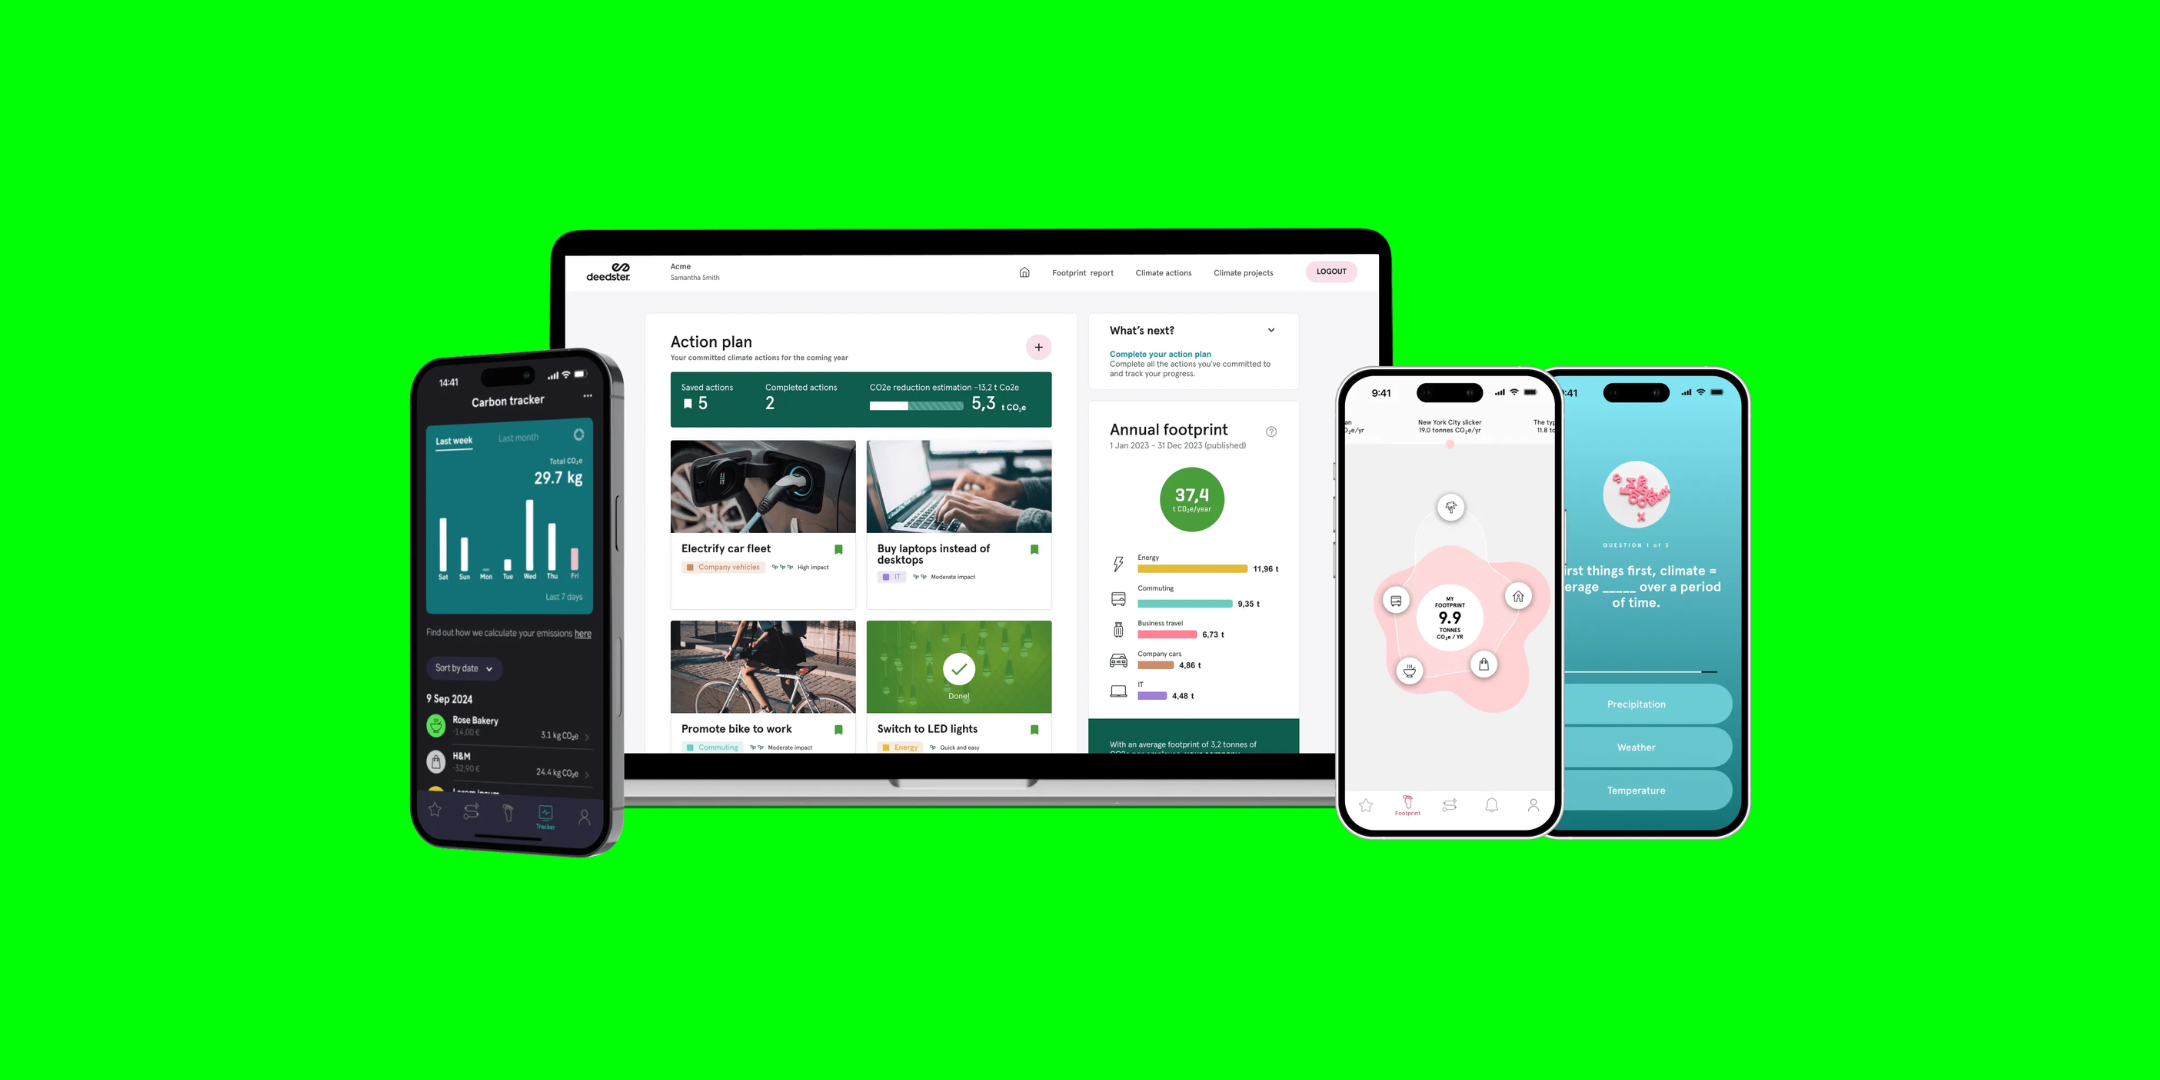
Past, present and future of the successfully merged scaleup.
Corinna Covini, Copenhagen Fintech: Deedster and Copenhagen Fintech share a birthday year. Can you take me back to the beginning and tell me what brought you into this journey?
Niclas Persson, Managing Director, Deedster: Deedster started almost 10 years ago, on the back of the Paris Agreement. It was 2016, and climate change had surfaced as an urgent topic on the global agenda.
We saw a clear need for data and digital tools that could help companies understand, measure, and act on their climate impact in order to meet the objectives and targets set by the Paris Agreement.
For us, this was an opportunity to build a company with a strong purpose. We wanted to build impact for profit, because we believed that the more impact our platform could create, the more value it could also create for customers, investors, and society. To this day, I still think that is the best possible combination.
Corinna: Deedster is now a scaleup that has successfully completed a merger. Can you share some of the pivotal moments behind that journey?
Niclas: There have been a few pivotal points for Deedster, especially in the constantly changing landscape of net-zero transformation and ESG.
One early moment came when, for testing purposes, we launched an app for individuals to understand the climate impact of their lifestyle, including spending, savings, and everyday choices. More importantly, the app helped users understand what they could do to reduce their impact on climate and the environment.
Originally, our main target was to reach consumers with a B2C service. But when we started testing it in company settings, the response was overwhelming. In 2016 and 2017, climate engagement was becoming a hot topic for companies, and suddenly we had a B2B service that we could sell to organisations embarking on their own net-zero transformation journeys.
That became a training ground for Deedster, but also a very strong early revenue stream. We worked with fantastic customers and users across more than 50 countries.
At one point, we signed a five-year global agreement with Swiss Re, covering 14,000 users in 23 countries. That gave us confidence, speed, and velocity.
But we also realised that we are fundamentally B2B people. We understood large corporates, banks, and financial institutions. So we pivoted the product towards embedded distribution through banking, card, and payment platforms. That decision paid off, because it gave us both a distribution model and a business model that made sense.
Corinna: How does the Deedster product look today?
Niclas: The evolution of the product is closely connected to the evolution of ESG, climate data, and net-zero transformation.
In the beginning, there was a lot of momentum driven by the alarming projections around climate change. Sustainability became a top priority for companies, consumers, and even politicians.
As that initial momentum cooled slightly, regulation came in to preserve some of it. In Europe especially, regulators introduced reporting directives and ESG disclosure requirements, which helped create demand in the sector. That demand was more focused on accounting, compliance, and reporting than on behavioural change and transition enablement, but it still supported parts of Deedster’s business.
The third waypoint is where we are now. Regulation has stepped back a little on a broader scale, including through the so-called omnibus changes and adjustments to CSRD requirements in Europe. For many companies, particularly SMEs, some of the mandatory reporting pressure has changed.
Today, the driver is increasingly climate risk and ROI. Consumers, companies, banks, and investors need to understand how climate change affects their everyday decisions, their assets, their businesses, and their portfolios. It becomes an integrated part of their business.
Heatwaves, storms, wildfires, flooding, and erosion are no longer abstract sustainability issues. They create physical climate risks, which become financial risks. They affect assets, investments, property values, insurance, lending, and long-term balance sheet exposure.
When it comes to losing money, big money and business, climate risk becomes very real and... hence ..interesting. Unfortunately, that is what it takes to accelerate transition. But then again, it is ia good thing
That is where Deedster is now adapting its platform: helping banks and their customers understand those risks, mitigate them, and take action.
Corinna: Let’s talk about the Climcycle acquisition. What are your hopes and ambitions for this next chapter?
Niclas: We have now become an integrated part of Climcycle, an Austrian company spun out of KPMG. Climcycle has built an impressive platform, originally designed by auditors for auditors, to meet the reporting, compliance, and risk management needs of financial institutions and banks.
As climate risk becomes more present on the balance sheets of financial institutions, there is a growing need for better data, better tools, and more granular risk assessment.
That is where Deedster fits in. We bring strong capabilities around retail banking customers, individual users, and SMEs. SME data is especially important, because small and medium-sized companies often do not report in the same structured way as larger corporates.
The merger starts there: Deedster feeds more granular customer and SME data into the Climcycle platform. We also bring our capabilities in measuring, explaining, and reducing carbon emissions through digital decarbonisation programmes and transition pathways for companies and banks.
Bringing that into Climcycle’s broader reporting and risk management environment plays really well together. Together, we can build a much more comprehensive offering for the Nordic and Baltic markets.
Climcycle is already well established in Central Europe, including Austria, Germany, and Poland. With Deedster, they can now bring stronger change-enablement tools and more granular data capabilities to more than 100 banks.
Corinna: You have been a long-standing member and partner of Copenhagen Fintech. How has the ecosystem supported you?
Niclas: I am an advocate for Copenhagen Fintech and an ambassador. I tell every peer in the startup and scaleup community that this is the place to be.
As a small company, we understood early that if you want to do business with banks and financial institutions, you cannot do every deal yourself. You need partnerships, trusted channels, and access to networks where you can reach the right people and manage long sales cycles.
Through Copenhagen Fintech, we joined delegations to Berlin, Zurich, Singapore, and Nordic Fintech Week. The quality of the network has always stood out, especially the supplier-buyer ratio. It is very clear that the team has been able to nurture an ecosystem of suppliers, partners, and buyers that is appreciated by all sides.
That is a key success factor for Copenhagen Fintech.
There is also a leadership culture of genuinely caring for partners and members in a way that I have not seen elsewhere. Copenhagen Fintech takes a long-term view, and that makes a difference.
Corinna: Where are we going to see you next?
Niclas: We were a little disappointed not to see ESG as one of the main themes at Nordic Fintech Week 2026, so we decided to take matters into our own hands and arrange an ESG forum.
Together with Climcycle, we will look at how physical climate risks affect banks, investors, and other market participants. We will discuss how those risks affect pricing, costs, customers, and the broader financial ecosystem, and in particular how banks can help their customers navigate this transition.
We are also using the opportunity to celebrate the merger, which took place earlier this year, together with the broad and deep network of institutions and banks we have worked with over the years.
I am extremely proud to present our wider platform and comprehensive offering. It now covers much more of a bank’s ESG and climate-risk agenda, including risk exposure, risk management, compliance, and transition enablement for banks and their customers.
Corinna: How do you see the future?
Niclas: As an entrepreneur, you almost have to be an optimist by definition. You always see the opportunity, and there is an opportunity to make quite rapid changes.
We are beginning to see what carbon emissions and climate risk could cost us in the future. As those costs become clearer, the appetite for change will increase.
It is going to become more costly before it gets better, but bankers, investors, and consumers will eventually be among the forces accelerating change for the better.
AI will also play a role, because it will help us understand more quickly what we can do, and what the implications are if we do not act. There is a downside, of course, especially the energy consumption of AI and data centres. But the answer to that is electrification and renewable energy.
Ultimately, AI adoption can also help accelerate the shift towards renewable energy and the retirement of fossil fuels.
Beyond Nordic Scaleup Program is powered by Industriens Fond.